When a company records a financial transaction or other accounting event—such as purchasing or selling an asset—it creates a journal entry detailing the activity.
Journal entries serve several purposes. In addition to capturing the details of a company’s transactions, journal entries:
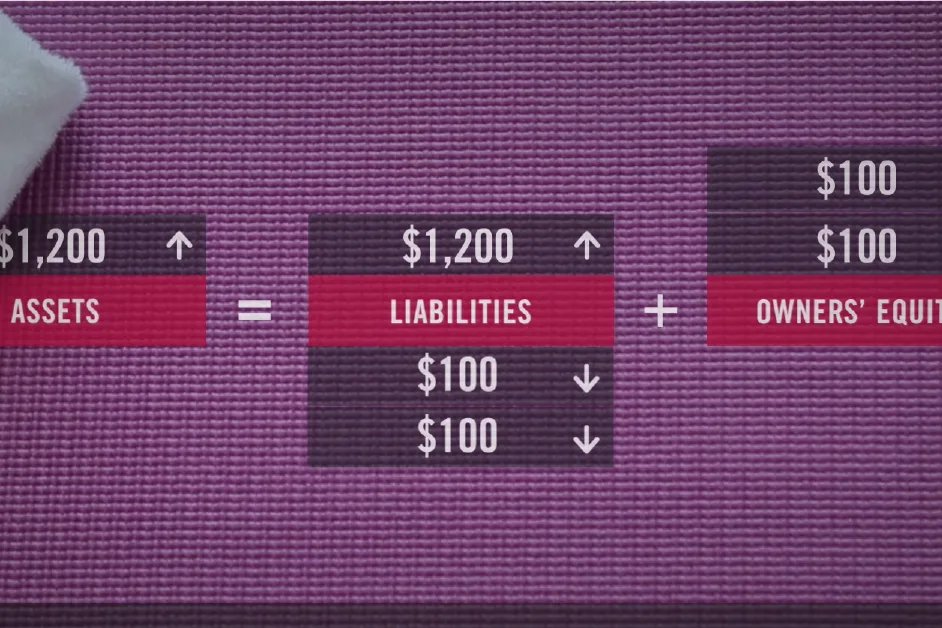
Keep the company’s accounting equation balanced using debits and credits
Feed transaction information into its general ledger
Supply the data needed to generate financial statements, like the balance sheet and income statement
Provide records for internal, financial, or tax audits
According to Harvard Business School Professor V.G. Narayanan, who teaches the online course Financial Accounting—which can be taken individually or as part of the multi-course Core Business Essentials program—most journal entries result from a specific transaction.
“Typically, these kinds of transactions involve some exchange of resources between two parties,” Narayanan says in Financial Accounting. “These transactions often come with invoices or documentation that initiate the recording and specify the components of a journal entry. We call these explicit transactions.”
Narayanan adds that not all transactions have an explicit trigger. Yet, they still need to be reflected in the company’s accounting records.
“These types of transactions often involve some degree of judgement in determining the timing and amount of the journal entries,” Narayanan says in Financial Accounting. “We call these implicit transactions.”
Implicit transactions often require a special type of journal entry called an adjusting journal entry. This guide explores what adjusting journal entries are and why they’re important in accounting. It also details common types of adjusting journal entries and examples to help you understand how they work in practice.
Featured Certificate Course
Financial Accounting
Learn how financial statements are built, interpreted, and used to assess business performance.
Start Anytime | 5 Modules | 8-9 Hours per Module | $1,949
What Are Adjusting Journal Entries?
An adjusting journal entry, or adjusting entry, is an update to a business’s general ledger that ensures revenue and expenses are recorded in the appropriate accounting period, and related account balances are accurate. Adjusting entries are usually made at the end of an accounting period, which can be monthly, quarterly, or annually.
As described in Financial Accounting, implicit transactions—and therefore, adjusting entries—don’t involve a specific triggering event, activity, or transfer of resources from one party to another. Instead, they’re often tied to financial activity or changes in value that occur over time and aren't captured by a specific transaction.
Indicators of implicit transactions include:
No transfer of resources
No invoices or other transaction documentation
No specific activity or event that clearly triggers the journal entry
The need for judgment to determine when and how much to record
Why Are Adjusting Journal Entries Necessary?
As discussed in Financial Accounting, adjusting entries are necessary because of how accrual accounting works.
Under accrual accounting, revenue is generally recognized when it’s earned, which may differ from when cash is received. Likewise, expenses are recognized when they’re incurred or as the related economic benefit is consumed, rather than when cash is paid. This differs from cash accounting, which records revenue and expenses when cash changes hands.
For example, imagine that a client prepays your company for a full year of services. Under cash accounting, all this revenue would be recorded when the payment is received. As a result, revenue would appear higher during that period and lower in subsequent ones.
Under accrual accounting, revenue would instead be recorded as it’s earned, regardless of when the customer pays, using adjusting entries. When the prepayment is initially received, it would be recorded as a liability rather than as revenue. Adjusting entries would then be used to recognize the appropriate amount of revenue each period as the company renders its services.
Another common example is prepaid expenses, such as auto or property insurance, where a single payment provides coverage for several months. In this case, the company would typically record the payment initially as a prepaid asset. Then, adjusting entries would periodically recognize the portion of the prepaid amount used during each period.
How Adjusting Journal Entries Work
Accountants typically make adjusting journal entries at the end of a company’s accounting period, before generating financial statements.
Usually, the process begins with the accountant reviewing account balances and identifying revenues, expenses, assets, or liabilities that need to be updated to accurately reflect business activity during the period. Adjustments may be necessary when a business has:
Used part of a prepaid expense
Earned a portion of prepaid or otherwise deferred revenue
Incurred an expense but not yet paid the corresponding bill
Completed work and earned revenue but not yet received payment
Once they’ve identified a necessary adjustment, the accountant determines which accounts are affected and the amount that must be recognized during the period. As with any journal entry, they use at least one debit and one credit to record the adjustment.
As Narayanan explains in Financial Accounting, the process of determining the accounts and amounts that must be adjusted is often a mix of art and science.
“The process of adjusting entries requires a certain level of judgment, and it's likely that given the same situation, two reasonable people arrive at two different conclusions,” Narayanan says in Financial Accounting.
After recording the adjustment, the accountant posts it to the company’s general ledger. This step updates the affected account balances. The accountant then typically prepares an adjusted trial balance to confirm that total debits equal and total credits. If they don't, the accountant must identify and correct the discrepancy. Financial statements can then be generated using the adjusted figures.
Featured Multi-Course Program
Core Business Essentials
Build fluency in the language of business and gain the confidence to make an immediate impact on your career and organization.
Self-Paced | 17 Weeks | 5-8 Hours per Module | $2,799
Types of Adjusting Journal Entries
There are multiple types of adjusting journal entries, each aligned with a different type of accounting activity. According to Financial Accounting, the four basic types of adjusting entries fall into two broader categories: accruals and deferrals:
Accrued revenues
Accrued expenses
Deferred expenses
Deferred revenue
Accruals recognize revenues that have been earned or expenses that have been incurred before the related cash is received or paid. Deferrals account for cash that's already changed hands before the related revenue is earned or expense is recognized.
Each of these types, as well as a few additional categories, is explored in greater detail below.
Deferred Expenses
When a company makes a payment before it incurs an expense—as might be the case with prepaid insurance premiums—it’s called a deferred expense. The transaction is initially recorded as an asset. As the company receives the benefit it paid for, a portion of the asset is recognized as an expense through an adjusting entry.
Deferred Revenues
Conversely, when a customer prepays for a company’s product or service, it's called deferred or unearned revenue because even though the business has received a cash payment, it hasn't yet done the work to earn the revenue. Unearned revenues create an obligation to the customer. These transactions are initially recorded as liabilities, and adjusting entries are made to reduce the liability over time as revenue is earned.
Accrued Expenses
Accrued expenses are financial obligations that a business has incurred but not yet paid. Common examples include property taxes, accrued interest, utilities, or payroll. Because these expenses have already been incurred, they need to be recognized in the appropriate accounting period even if the business hasn't yet made a payment. This is done via an adjusting journal entry, which records the expense and a corresponding liability that remains on the balance sheet until it's paid.
Accrued Revenues
Similarly, if a company has performed work for a client but has not yet billed them or received payment, the accrued revenue still needs to be recognized in the appropriate accounting period. An adjusting entry is made to record the revenue and a corresponding asset, typically accounts receivable. This asset remains on the balance sheet until the client pays for the services.
Other Types of Adjusting Entries
While the four types discussed above are the most common basic types of adjusting entries, they're not the only ones. Other categories to be aware of include:
Depreciation, which involves allocating the cost of a depreciable asset—like a building, vehicle, or piece of equipment—over its useful life
Amortization, which involves distributing the cost of intangible assets, such as patents, copyrights, and licenses, over their useful lives
Allowances for bad debt, which account for the portion of accounts receivable that a company estimates it may not collect from its customers
Examples of Adjusting Journal Entries in Action
The following examples show how adjusting entries work for deferred and accrued expenses.
Deferred Expense Example
For deferred expenses, imagine that a company pays $12,000 upfront for an entire year’s worth of property insurance. The company initially records the entire payment as a prepaid insurance asset. At the end of the month, it needs to make an adjusting entry to recognize $1,000 of that amount as an expense, which would typically look like this:
Insurance Expense: $1,000 debit
Prepaid Insurance: $1,000 credit
In this case, the debit recognizes the insurance expense that was incurred during the month, while the credit reduces the balance of the prepaid insurance asset by the same amount.
Accrued Expense Example
For accrued expenses, imagine that a company’s employees have earned $5,000 worth of wages at the end of the accounting period, but due to its payroll schedule, it won’t actually pay them until the following period. To account for this, the company would need to make the following adjusting entry:
Wages Expense: $5,000 debit
Wages Payable: $5,000 credit
Here, the debit recognizes the accrued wages as an expense in the period that the employees earned them, while the credit records that same amount as a liability until the wages are paid.
Free Brochure
Core Business Essentials
Build fluency in the language of business and gain the confidence to make an immediate impact on your career and organization.
Closing the Books with Confidence
Whether you’re a current or aspiring business owner, financial professional, or manager, understanding how adjusting journal entries help close the books each accounting period can strengthen your grasp of your organization’s financial information.
Preparing adjusting entries requires a solid foundation in accounting fundamentals, from debits and credits to accrual accounting. An online course like Financial Accounting, or a multi-course program like Core Business Essentials, can help you build those skills and apply them in your career.
Are you interested in strengthening your financial understanding? Explore Financial Accounting—which can be taken individually or as part of our online Core Business Essentials credential program. To learn more about Core Business Essentials, download our free brochure.